

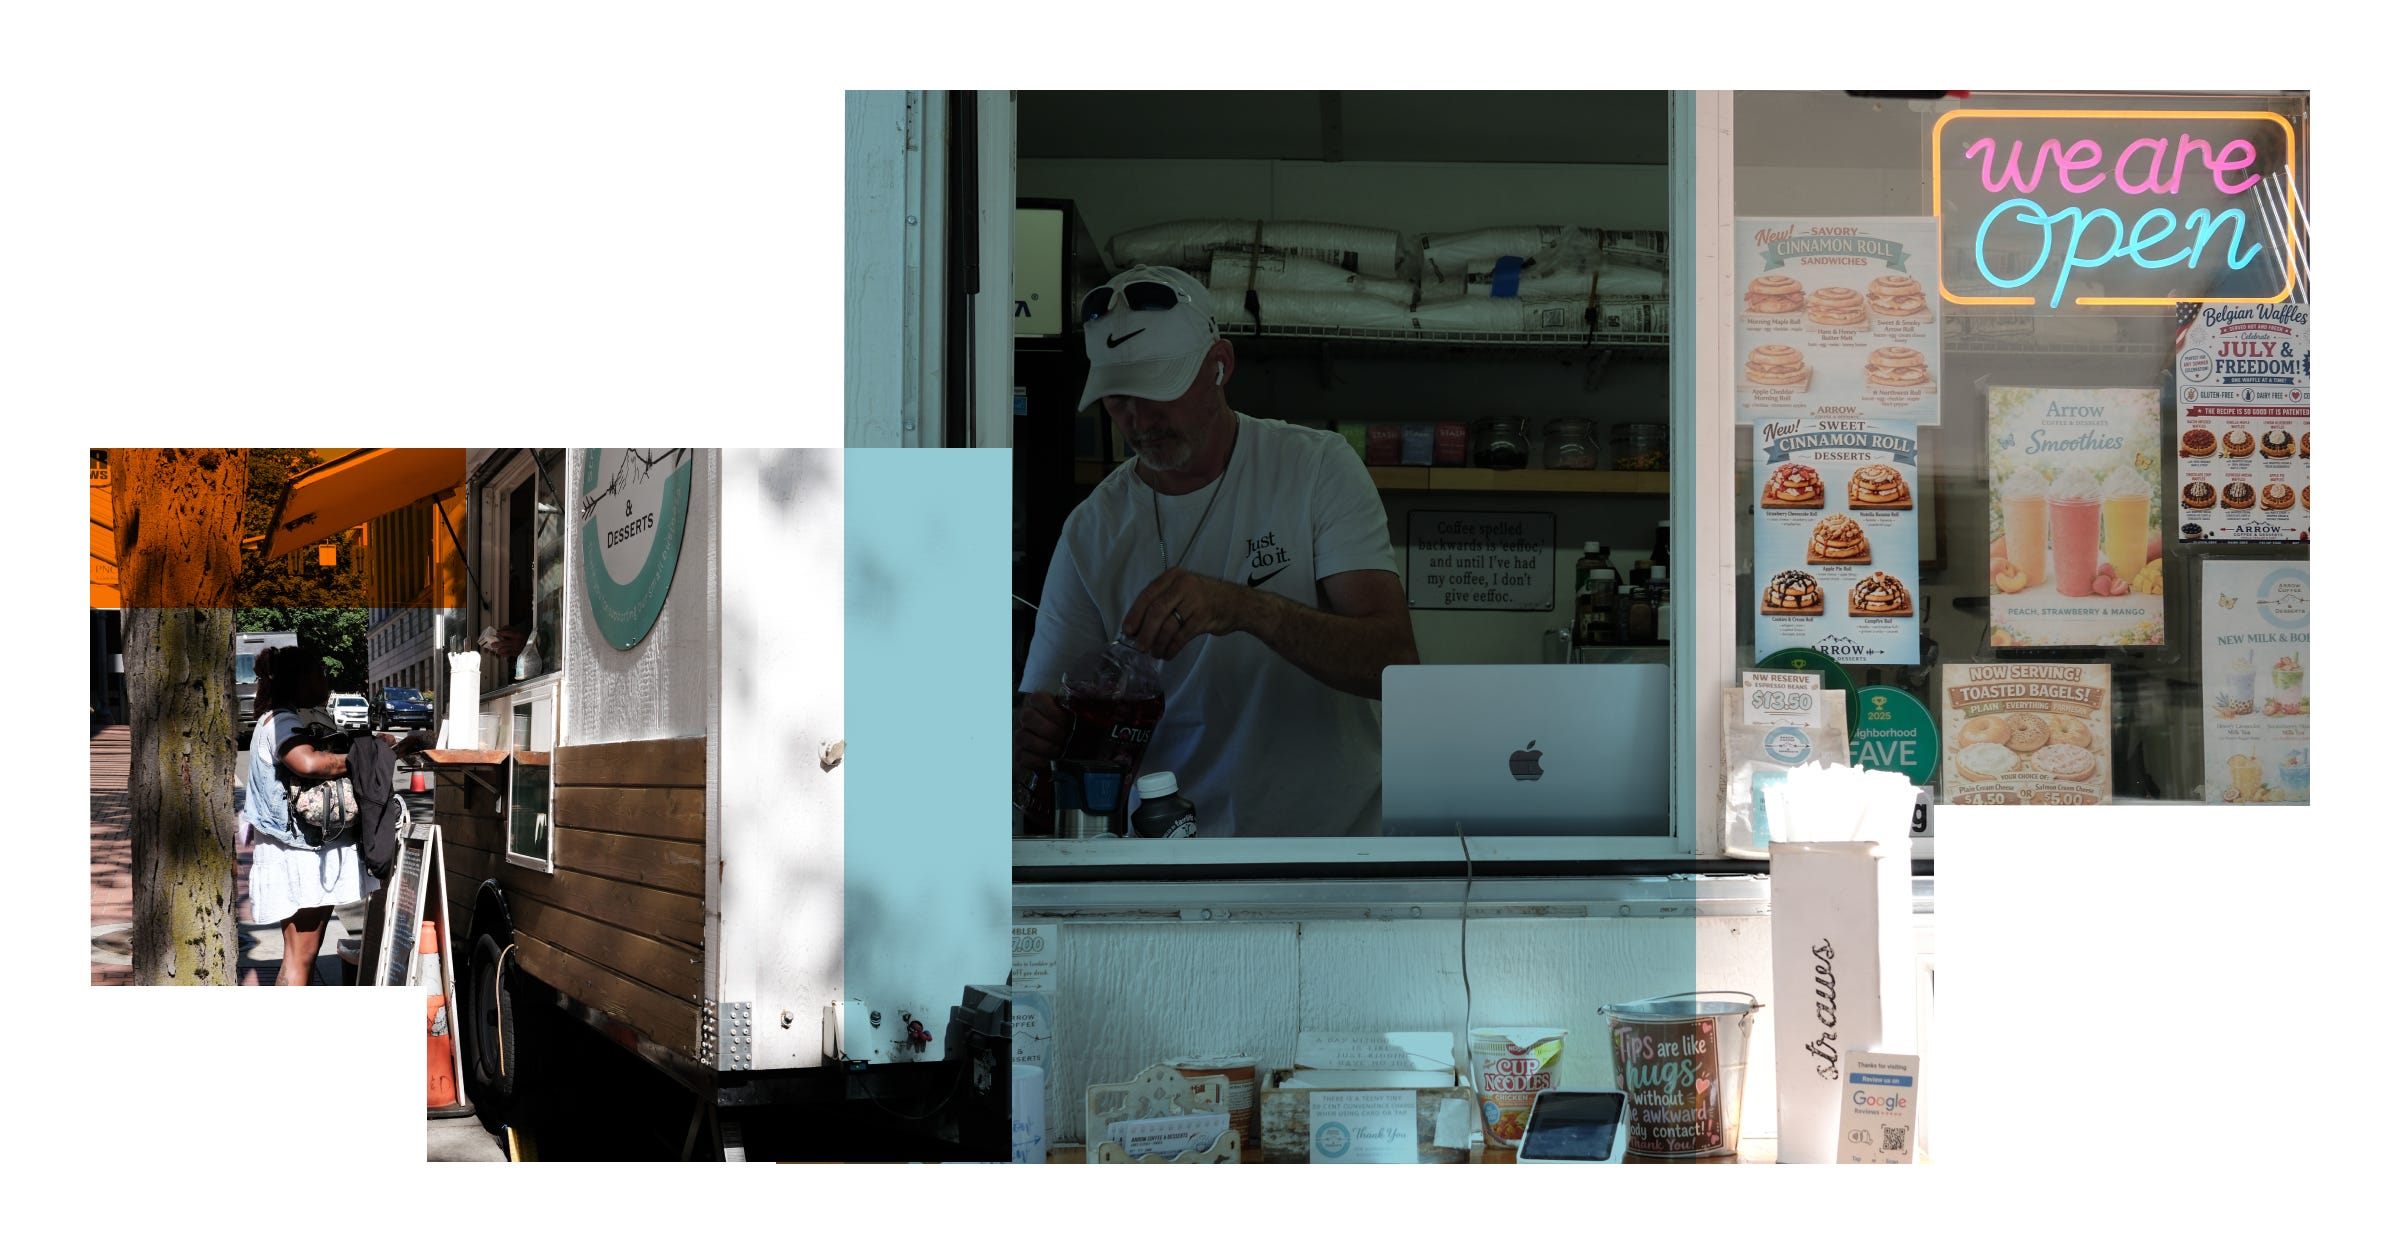
There is a coffee trailer parked at 5th and Madison most days; you’ll see it when you walk past City Hall, or when you step out of a meeting at the PacWest tower. Arrow Coffee & Desserts looks natural here – Portland is a food truck city, after all. What’s surprising is that Arrow Coffee & Desserts is parked in front of a vacant former Starbucks.
The coffee cart is popular, so you will have plenty of time waiting in line to ask yourself: why does the cart work where the shop failed? What has to be true about the economy for this to be the best solution? What makes this make sense?

If you’re lucky, you’ll get to meet Aimee, the founder of Arrow Coffee & Desserts, and her perspective will go a long way toward answering your questions.
“Tons of people who work in the building became customers of ours and kept telling us: ‘we are so happy you’re here. We can’t believe Starbucks left.’ Our customers keep suggesting that we open a storefront here… We’re parking in front of this beautiful, empty retail space that I have stared at for months. It is an incredible space and I can clearly see the vision.”
She hasn’t leased it. Although the vision is clear, a coffee shop in the former Starbucks space doesn’t work – at least not with the current variability in foot traffic, the standard ten-year lease terms, and the high fixed operating costs that come with a conventional brick and mortar café.
“I don’t have the right words to describe what I see,” Aimee said. “It’s backward.” She’s right – it’s backward because Arrow Coffee & Desserts gives the PacWest tower more than the tower gives back. The coffee trailer is a reason for tenants to come down in the morning, and a lively line of people that welcomes any prospective tenants touring the floors above.
The PacWest building is a barometer for retail across Portland. In areas with the weakest demand for upper-floor spaces, building owners no longer see the ground floor as a place to turn profit – they can’t find tenants to fill it. Instead, the ground floor is about creating vibrancy and demand. That’s why Arrow Coffee & Desserts operates through an arrangement that looks nothing like a retail lease.
Food trucks like this one thrive in 2026 downtowns because they’re built for volatility – a contrast made vivid in the comparison between the fortunes of Arrow Coffee & Desserts and Starbucks – so it’s tempting to focus on food trucks in lieu of storefronts. But a city filled with mobile operators is a city of failing buildings. The real project ahead is to bring the economics of food trucks indoors.
Building owners and policymakers have an opportunity to write a new operating system for ground floor retail that reflects the new fundamentals of demand – one that is closer to Arrow Coffee & Desserts than to Starbucks. What’s working and not working here at PacWest sheds light on models that are not only more effective (for property owners and vendors) but also more resilient to the urban economy of 2026 and beyond.
Two capital structures
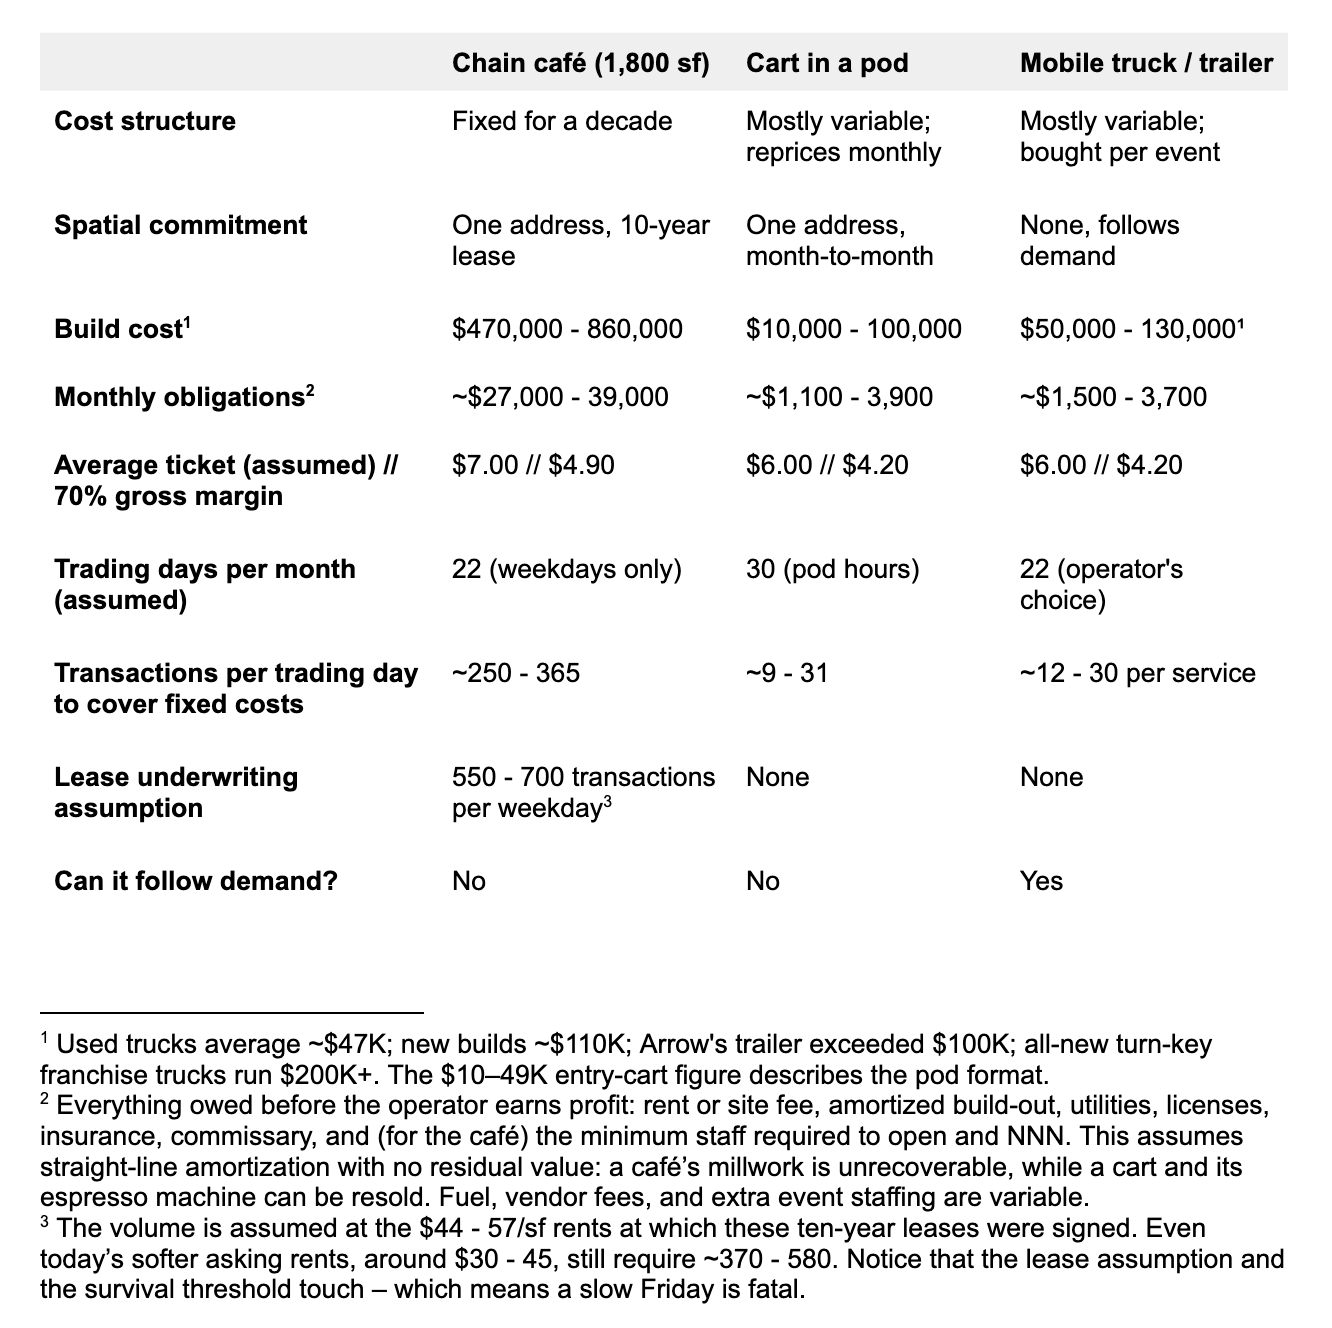
A Starbucks lease is a high-value, long-term transaction. Building out the café costs between $470,000 and $860,000.1 The immense up-front cost, which is typically split between the building owner and operator through a tenant improvement allowance, can only be justified by amortizing it out over a ten-year lease. According to industry conventions, a café is viable when the cost of occupancy (rent plus triple nets) runs about 8% of sales. The rest of the revenue covers the costs of consumables, labor, advertising, amortized tenant improvements, etc. The average Starbucks needs 550 to 700 transactions each weekday to keep rent at a healthy share of sales, and the company negotiates its leases accordingly.2
A conventional ten-year Starbucks lease is structured, priced, and underwritten on the premise of five identical mornings and ten years of predictable demand. In a central business district – and especially the PacWest tower, across the street from City Hall and beneath 30 floors of professional services firms – that premise looked like a sure bet when the lease was signed in the mid-2010s.
Today, employees come to the office at the center of the week, if at all. Tuesday through Thursday carry about 70% of weekday office visits. Historically, more than half of a chain café’s revenue comes in before 11am. The morning window from 7 to 11 saw the greatest declines between 2019 and 2025, according to data from Placer.ai.
Even as the “curve” of a work week shrinks, flattens, and becomes more variable, Starbucks still has to pay for it high fixed costs. The share of sales allocated to rent has crept from 8% to 11% to 15% or more. A ten-year lease underwritten for five mornings can’t be repriced when two of those mornings disappear and the remaining ones falter. In 2025 Starbucks did the math and chose to close 627 stores in a single quarter, paying roughly $450 million to break its leases. A disproportionate number of the terminated locations were the seatless pickup format engineered for a now-nonexistent commuter rush.
Aimee is intimately familiar with the new, emergent workday patterns. “Nine to ten we have our morning push, then again during lunch from noon-one – and then it dies. After two o’clock, it is a ghost town.” It doesn’t take long for an operator like her to understand and begin predicting these patterns – she can open, close, or even move Arrow Coffee & Desserts around town to follow demand.
A truck can flex into the work weeks and work locations that people actually work in 2026 – and it can shift to any other location and opening hours overnight. Arrow Coffee & Desserts caters to events like the Portland Marathon. “There are typically 20,000 attendees,” she said, “and they’re going to want their coffee before their race.”
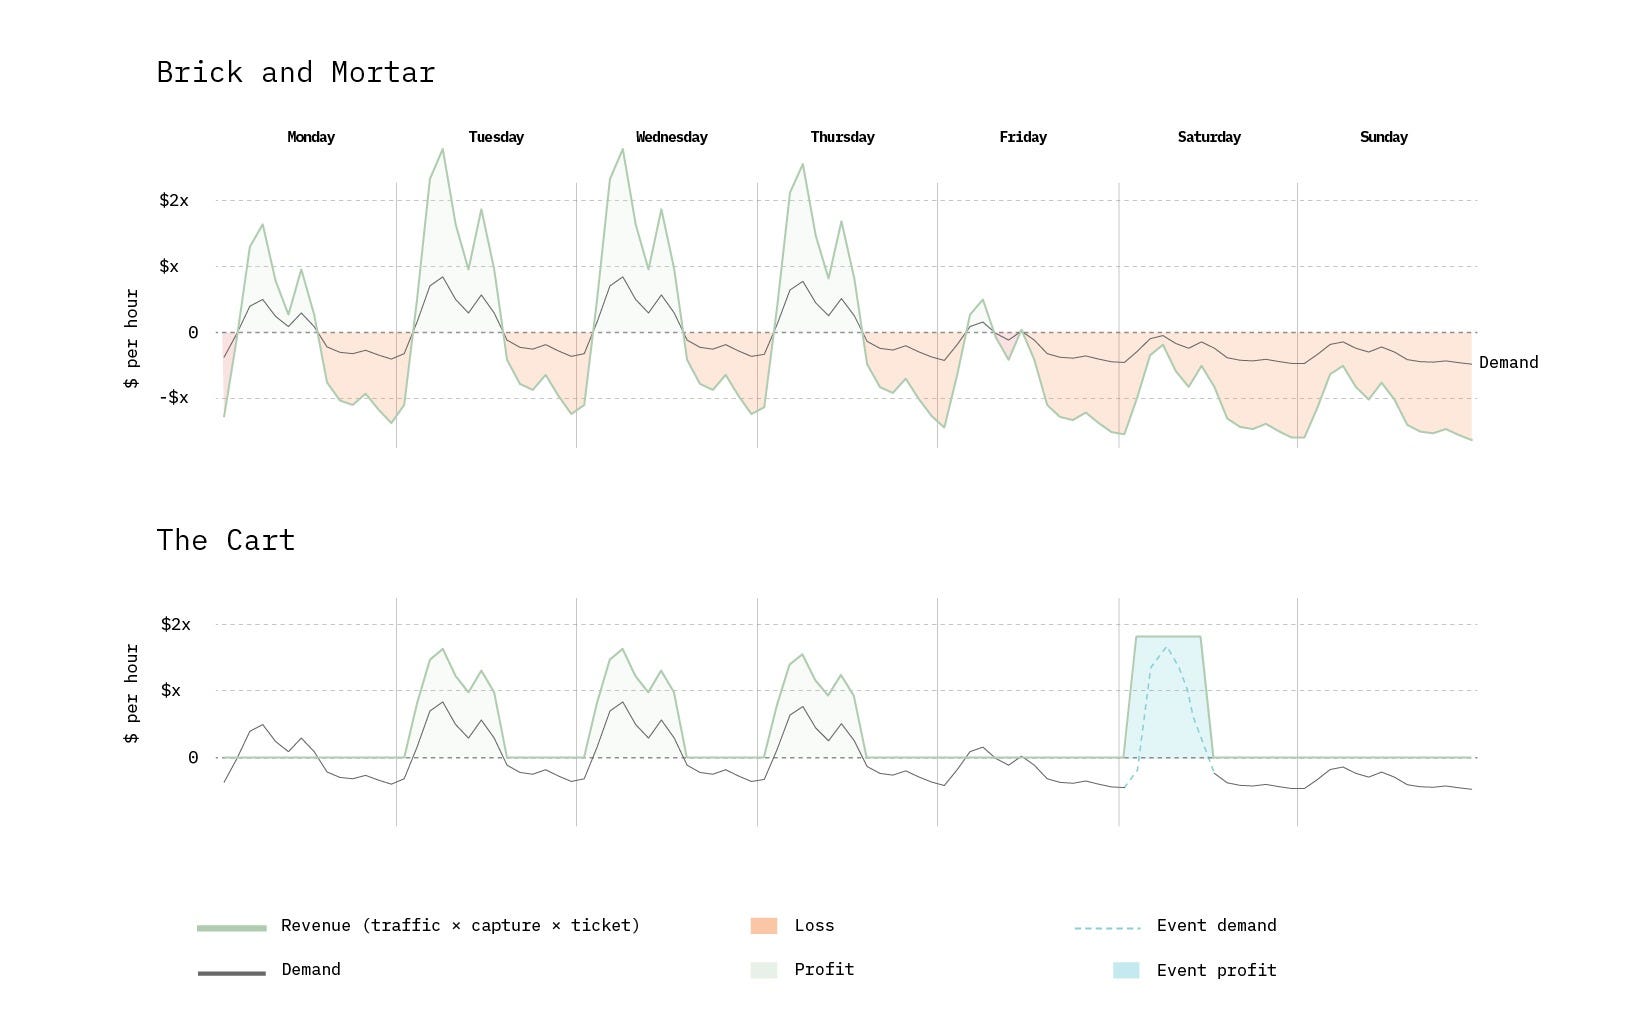
Even if Starbucks could close early when demand slows and save a bit on hourly staff wages, it would still have to carry the fixed cost of amortized tenant improvements and a ten year lease – that’s the difference between fixed and variable costs. Fixed costs are owed whether or not a customer turns up, variable ones rise and fall with revenue. A café makes more than a cart when it’s running at full capacity, but it also loses more at all times. A food truck, on the other hand, can close or move to follow the energy of its customers. When demand is variable, the mobile unit has a clear advantage over the storefront.
A new rent threshold
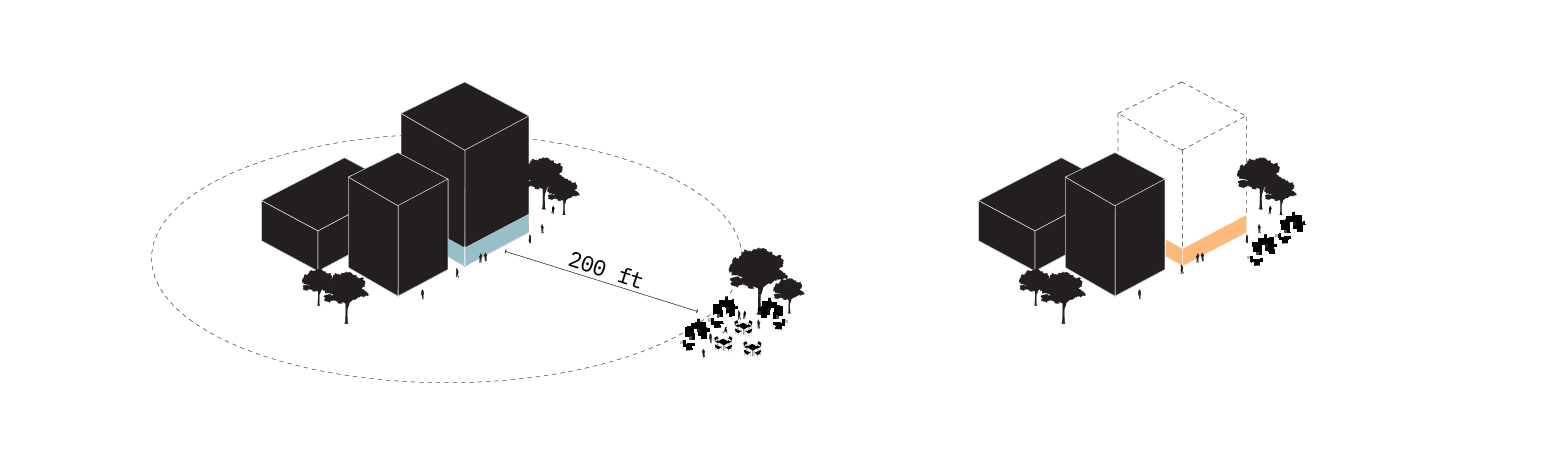
The conventional view of the food truck-storefront relationship was perfectly illustrated and legally codified in a landmark case at the Illinois Supreme Court. In 2012 the City of Chicago passed a comprehensive mobile food vendor ordinance that included a 200-foot exclusion zone around brick and mortar restaurants, and required food truck operators to install GPS trackers to prove their compliance.3 It took until May 2019 for LMP Services v. City of Chicago to make its way to the state’s highest court, which held that the City has a legitimate, rational interest in protecting traditional brick and mortar restaurants. The ruling reasoned that restaurants generate vital local tax revenues and economic benefits – casting the truck as a free-rider poaching foot traffic from fixed locations that pay rent, taxes, and tenant improvements to fixed spaces.
In a healthy downtown with predictable foot traffic, high office lease rates, a dynamic real estate market, and healthy municipal property tax revenue, this perspective makes sense. When an office building is operating below 70% occupancy and building amenities are a crucial factor in the prospects of leasing upper floor spaces, the ground floor takes on a new role. Brookfield and JBG Smith, among the largest office landlords in the country, schedule food trucks at more than 150 of their buildings. Platforms like Curbside Kitchen and Suburban Events – which programs PacWest tower – bring local food trucks to office towers.4
This is an opposing view of the truck: not a free-rider, but a vital contributor to the viability of the building, feeding tenants, animating the street, and driving demand for the office space by differentiating the building in a competitive market. Far from a free-rider to be excluded, the truck is a prize worth paying for.
A market-clearing rent happens when a tenant and landlord reach an agreement about value. It is hard to disentangle the direction of causality, but the reality today is that ground floor operators create value for building owners, and rent is falling.
Buildings’ balance sheets are starting to reflect the new conditions. Property owners around Portland are looking for tenants at any rent, in some cases as low as $0. This is a play from the classic suburban mall playbook. Anchor tenants like Macy’s never paid full freight – every other tenant subsidized their rent.5 Food and coffee trucks are the micro-anchors of Portland’s empty office towers.
When Starbucks gave up its lease, Arrow Coffee & Desserts effectively became the building’s café amenity, but it did not commit to a 10 year lease. Instead, the frontage is programmed by Suburban Events, a food truck booker that holds the permit from the Portland Bureau of Transportation. Suburban Events and PacWest share the permit costs, and Arrow Coffee & Desserts, along with a rotating cast of food trucks, pays Suburban Events a share of daily revenue. Most trucks that work with Suburban Events have a minimum guarantee – around $400 to $800 per service. If sales come in under that floor, the sponsoring building owner is responsible for paying the difference (plus a tip) to the truck operator.
The arrangement is novel for Portland. The Arrow Coffee & Desserts trailer occupies the parking lane – a public right-of-way where city code PCC 16.20.150 has, for decades, prohibited vehicle vending. In January 2024 the parking lane in front of PacWest opened up as part of PBOT’s Food Truck Pilot Program run exclusively with Suburban Events. The company works with dozens of locations and food trucks in the Portland metro area, bringing a rotating menu of vendors to buildings, neighborhood associations, office parks, and breweries full of customers.
Suburban Events’ website reads “we understand from data and experience what types of locations produce the highest yield of customers.” The subtext is that ground floor demand dynamic is not happening ubiquitously across the city, or even across downtown. The average price of market-clearing rent and aggregate occupancy rate can be thought of as a block’s “health.” Health determines the likelihood of a property owner fielding multiple offers from prospective brick and mortar retailers willing to pay rent – versus paying for a truck to turn up in front of a vacant retail space.
Here again Arrow Coffee & Desserts is a good example: Aimee has experience at both ends of the spectrum. On a handful of prime blocks, such as Vancouver’s new waterfront, demand holds, and a fixed retail space is viable for a brick and mortar café. Aimee is actively exploring this opportunity, but acknowledges that “to be at the ‘it’ spot, you’re going to pay the price.” PacWest is at the other end of the spectrum, and it’s not alone.
We have run this experiment before
Food carts are an indicator of the building economics behind them – a role they’ve played through decades of Portland real estate cycles, as land availability and value fluctuate. The history runs in three acts.
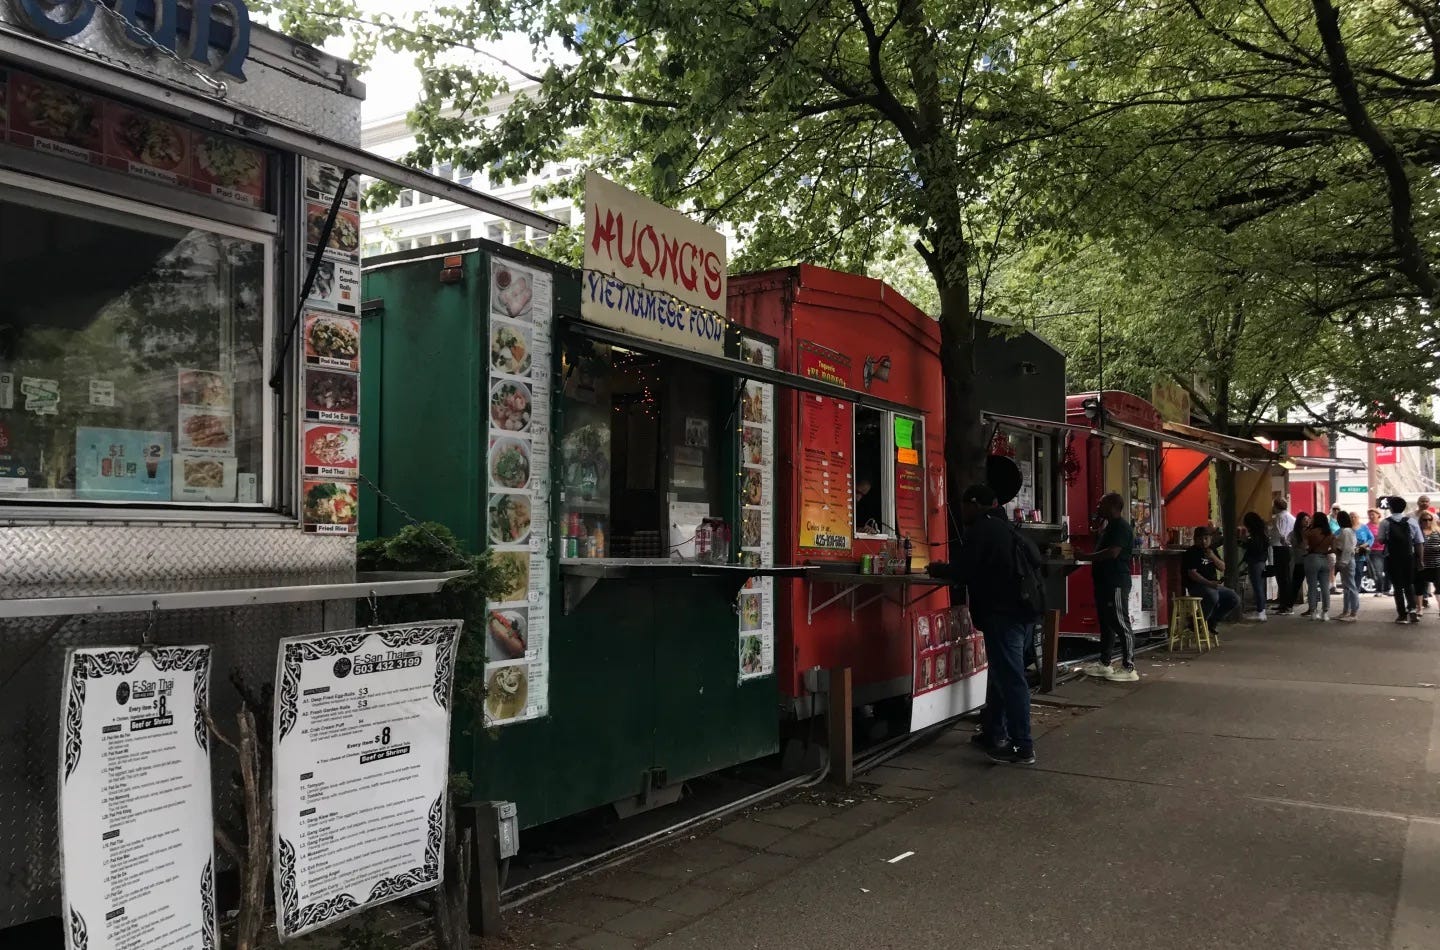
Act I: abundance. Food Cartology, released in 2008, documents the policy foundation behind a thriving food truck economy. A restaurant with wheels and a towing axle is legally deemed a vehicle – and therefore does not require complex permits. Parking lot owners were happy to lease to trucks while waiting for development opportunities. Surface lots were the best home for trucks, as City code prohibited vending from a vehicle parked at the curb, and sidewalks allowed only push-cart-scale permits. In the early 2000s, many surface lots were formalized into “pods” – a distinctively Portland format that brings together 3-10 food trucks on a site with basic shared infrastructure. At the time, spots in these pods ran $500 to $600 a month. Protagonists of the burgeoning food truck scene had ambition: more than half of the vendors interviewed dreamed of graduating from a truck to a storefront.
Act II: displacement. Food trucks became the crackling experimental edge that gave Portland a unique flavor – and national recognition. The truck was a low-risk, low-cost format that served as an on-ramp for entrepreneurs. In 2008, Food Cartology documented a single transition from cart to storefront, but it was eventually followed by Nong’s Khao Man Gai, Lardo, Salt & Straw, Matt’s BBQ, and Bing Mi, among many others – businesses that have defined Portland’s identity as a food capital. But, as Portland’s food truck scene blossomed, cheap surface lots became scarce. Land values recovered through the 2010s, and parking lots were incrementally developed.6 The tension reached a climax in June 2019 when the Alder Street pod, downtown’s largest, home to around fifty carts, and the one The Amazing Race had broadcast to the world, was cleared to make way for the Block 216 development.
Act III: courtship and confusion. Five years after clearing the Alder Street pod, the City allocated $269,000 to situate food trucks at Ankeny Square. PBOT’s two-year Food Truck Pilot opened parking lanes for vehicle vending in 2024 (paving the way for Arrow Coffee & Desserts). In 2025, obtaining a license to vend at 41 city parks became a same-day permit that costs $5 per day. While the city has prioritized food trucks, the County has threatened to raise health license fees 33%, and is now implementing a 6.5% increase (2026-27). Pod sites run $750–$2,400 a month. Oregon Health Authority rules issued in 2020 went into effect in Portland in 2023, and are reaching a compliance deadline this year. Those rules place significant infrastructure costs on property owners, and some cannot keep their pods open in compliance. Different levels of government are stepping on the accelerator and brake at the same time.
Portland is entering Act IV. Hundreds of storefronts are vacant. In some neighborhoods and buildings, ground floor retail rent is effectively zero: building owners will lease a space for only the cost of triple nets. But vendors no longer have much interest in moving from a truck to a brick and mortar space. Kim Jong Grillin’, a cart celebrated in local and national outlets, is perhaps the most telling. It went from a cart to brick and mortar and back to a cart in 2025, and now offers catering to diversify revenue. The markers of success, for some truck operators, have changed.
Four instruments
Food trucks remain a vital part of Portland’s food scene and broader identity, and they are well suited to the present economy. A cart can run laps around a brick and mortar, flexing with increasingly variable demand. Where downtown is suffering most, food trucks are an important tool not only for bolstering a building’s leasing prospects, but also improving the life of the street for all Portlanders.
It’s tempting to extrapolate the success of the food truck as a model, and make an argument for buildings to turn inside out. The food truck is a retail format fit for the economy of 2026!
But more food trucks isn’t necessarily the answer. Taken to the extreme, a city of food trucks is alive at eye level and insolvent above it. Trucks can animate sidewalks, but they can’t retire mortgage debt, maintain façades, or contribute to a building’s property taxes. In the long run, a city fails when its buildings fail, and food trucks can’t carry the City’s budget.
Today’s political focus on food trucks is encouraging, but myopic. There is an opportunity, instead, to learn from what is making trucks successful today, as a starting point for retooling Portland’s ground floor. Vendors, building owners, and policy makers must explore new models – and the advantages of the truck should be design specs for storefronts.
Instrument one – regulatory parity downward. Launching a storefront should be as cheap and reversible as launching a truck: pre-approval for activation-ready space; by-right or fast-track temporary occupancy for low-risk uses (similar to the cart-as-vehicle hack, made intentional and moved indoors); fee waivers when carts graduate to storefronts. Most importantly, align the public sector: city, county, and state postures.
Instrument two – the percentage lease. Building owners price a base rent low enough that a slow month doesn’t kill the operator and agree on a gross sales threshold above which the owner and vendor share the upside. Percentage rent is nothing new – it’s a standard tool for retail leases, especially in shopping malls. Here the old logic can be rebuilt for situations where the landlord needs the activation and the tenant faces significant uncertainty in future sales. Suburban Events, and their contract with Arrow Coffee & Desserts, is a working precedent. Today the revenue share is with the broker who holds the permit; a percentage lease would align incentives directly between tenant and landlord.
Instrument three – the shared data. If incentives are aligned, the owner and tenant have a reason to share information. Each has data from which the other can benefit to reduce risk or more effectively capture opportunities: transactions, leasing (actual and prospective), foot traffic, events, and neighboring properties. Here again, Suburban Events is a precedent – it offers forecasting based on past data as a value proposition to food truck operators. With good data, they can plan and flex intelligently. A fixed location can get closer to “following demand” the way a cart does – driving inbound traffic and opening when demand is greatest. Shared data can also help surrounding building owners price their leases. A food truck’s receipts are a signal in a district with no recent building transactions. Owners and brokers should treat them as a stand-in for a missing comp set.
Instrument four – the alternative use. Where retail cannot work at any rent, arguing about the lease is a mistake. In these situations, alternative ground floor uses may be more viable. Retail spaces can be used for small-batch makers / light production (think: Orox Leather), neighborhood services, micro-logistics, live-work, residential, or arts and culture. The blocker is convention, not viability. Building appraisals and financing often still assume ground floor = retail, but the viability of tomorrow’s programmed, non-retail ground floors should be evaluated with financial models designed to understand them.
Now what
There is a real risk of continued real estate market collapse downtown. But Portland is a food city, and trucks are a recovery instrument. Value is flowing between food trucks and buildings in new ways: Aimee is showing that a mobile trailer can work in Portland, just as she proves a storefront cannot – and by negotiating for a brick and mortar space across the river, she’s showing that the numbers aren’t permanently or ubiquitously “backwards.”
The city’s sidewalk vending experiment goes to council for a permanent decision this year. Property owners and policy makers have their pencils out – now is the moment to rewrite the regulatory and financial operating system, not just for the curb, but also for the ground floor. Regulatory parity, along with shared data and streamlined changes of use, will bring food truck dynamics indoors and foster a generation of creativity on the blocks that need it most. The entrepreneurs who will define Portland’s food, culture, maker and arts scenes are here, and they need low-barrier entry points to prove what they can do.
The $470–860K figure is the national quick-service-restaurant tenant-improvement range ($260–480 per gross square foot, according to Terrapin's 2026 TI guide), multiplied by a ~1,800 sf standard café and a Portland construction cost index. That’s a first-generation, corporate-spec fit-out of a shell space. In 2025 Starbucks disclosed that major renovations alone were running $800K–$1M per store. An independent café operator will build to a more reasonable spec, usually between ⅓ and ½ of Starbucks’ cost per square foot.
At 550 transactions x $7 = $3,850/day, 8% occupancy is $308/day. Hold rent flat and drop volume to 250/day and $308 is 17.6% of sales. These numbers are calculated based on Starbucks’ financial releases – see the FY 2025 results.
In this landmark case, The Institute for Justice, on behalf of plaintiff LMP Services, argued that the rules violated due process and constituted an unreasonable search.
This trend pre-dates the pandemic. Even in 2019, property owners were scheduling food trucks to differentiate their buildings in a competitive office market. What was a differentiator became a lifeline for struggling building owners after lockdowns (Bisnow).
Malls are designed to extend a visitor’s journey before reaching the destination anchor, giving them plenty of opportunities to discover (and spend money in) smaller shops. The theory justifying the comparative rents is that these smaller shops benefit from the foot traffic anchor retail attracts.
Willamette Week pronounced “the death of Cartopia” in 2014, as the land underneath the famous food cart pod was sold to a developer intent on building. The obituary turned out to be premature (Cartopia survived) but the thrust of the article was accurate: when the owner of a piece of land decides, with enough certainty, that a future building will be more profitable than a present food truck pod, they will generally start constructing. The article begins bombastically: “Burn every guidebook to Portland. They don’t make sense anymore. Because every single one of those books will tell Portland visitors to go to Cartopia, at Southeast 12th and Hawthorne, the city’s most iconic food cart pod. And after the carts’ leases expire in October, Cartopia will probably not exist.” Although Cartopia survived, the Willamette Week struck a resonant chord.
No mention of graffiti, vandalism, shop lifting and street mis-behavior? Not all cities tolerant them, so they are not uncontrolled externalities. A lot of this analysis just prices in the cost of ineffective government.