


To buy carpet is to be overwhelmed with options; loop pile, wool, nylon. It is not the most expensive flooring option (compared to, say, hardwood) but it’s easy to spend over $20 per square foot on nice material and installation in a commercial building.
Or, for about the same cost, you could just buy the building.
In December of 2025, Portland’s Commonwealth building sold for approximately $29 / square foot. The building isn’t a dump. Designed in 1948 by Pietro Belluschi (the same architect as Big Pink) and originally known as the New Equitable Building, this 14-story tower is clad in blue-green glass and aluminum. It is architecturally significant: it was the first modern curtain-wall building in America, the first to be sheathed in aluminum, double-glazed, fully sealed, and air-conditioned. The Commonwealth predates New York’s more famous Lever House, and it set the standard for what a corporate building should look like. It was the Armani suit of architecture; this building taught every office tower after it what to wear.
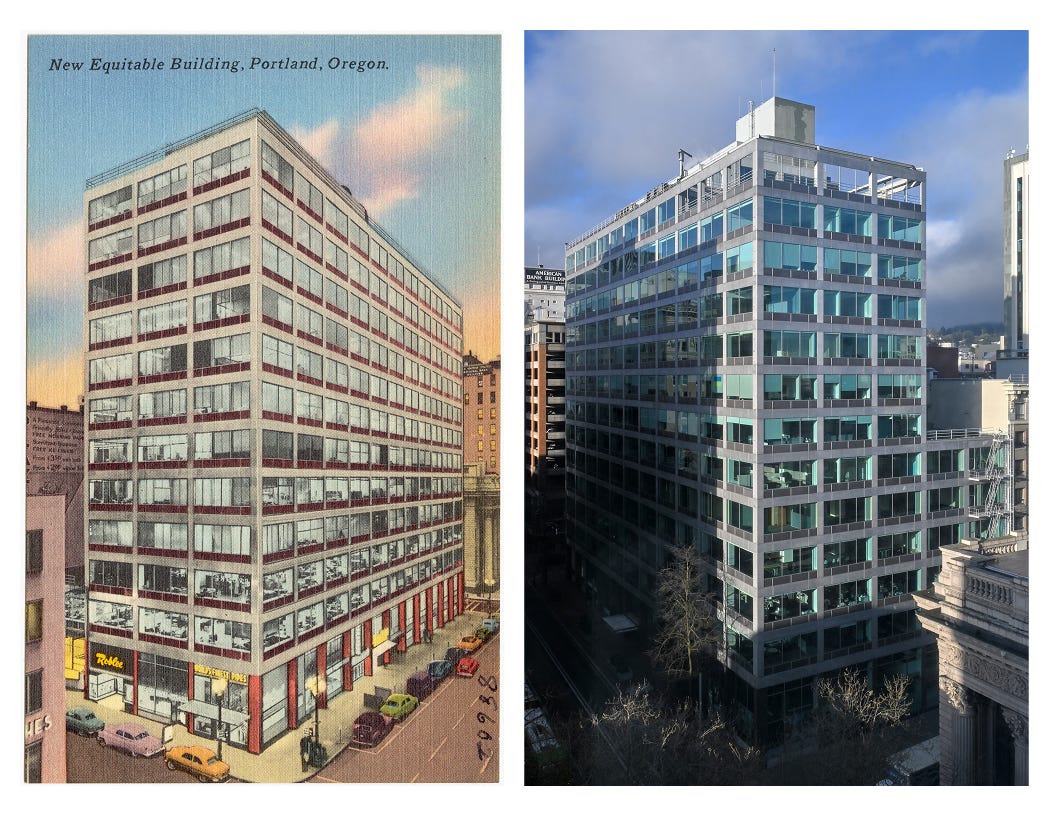
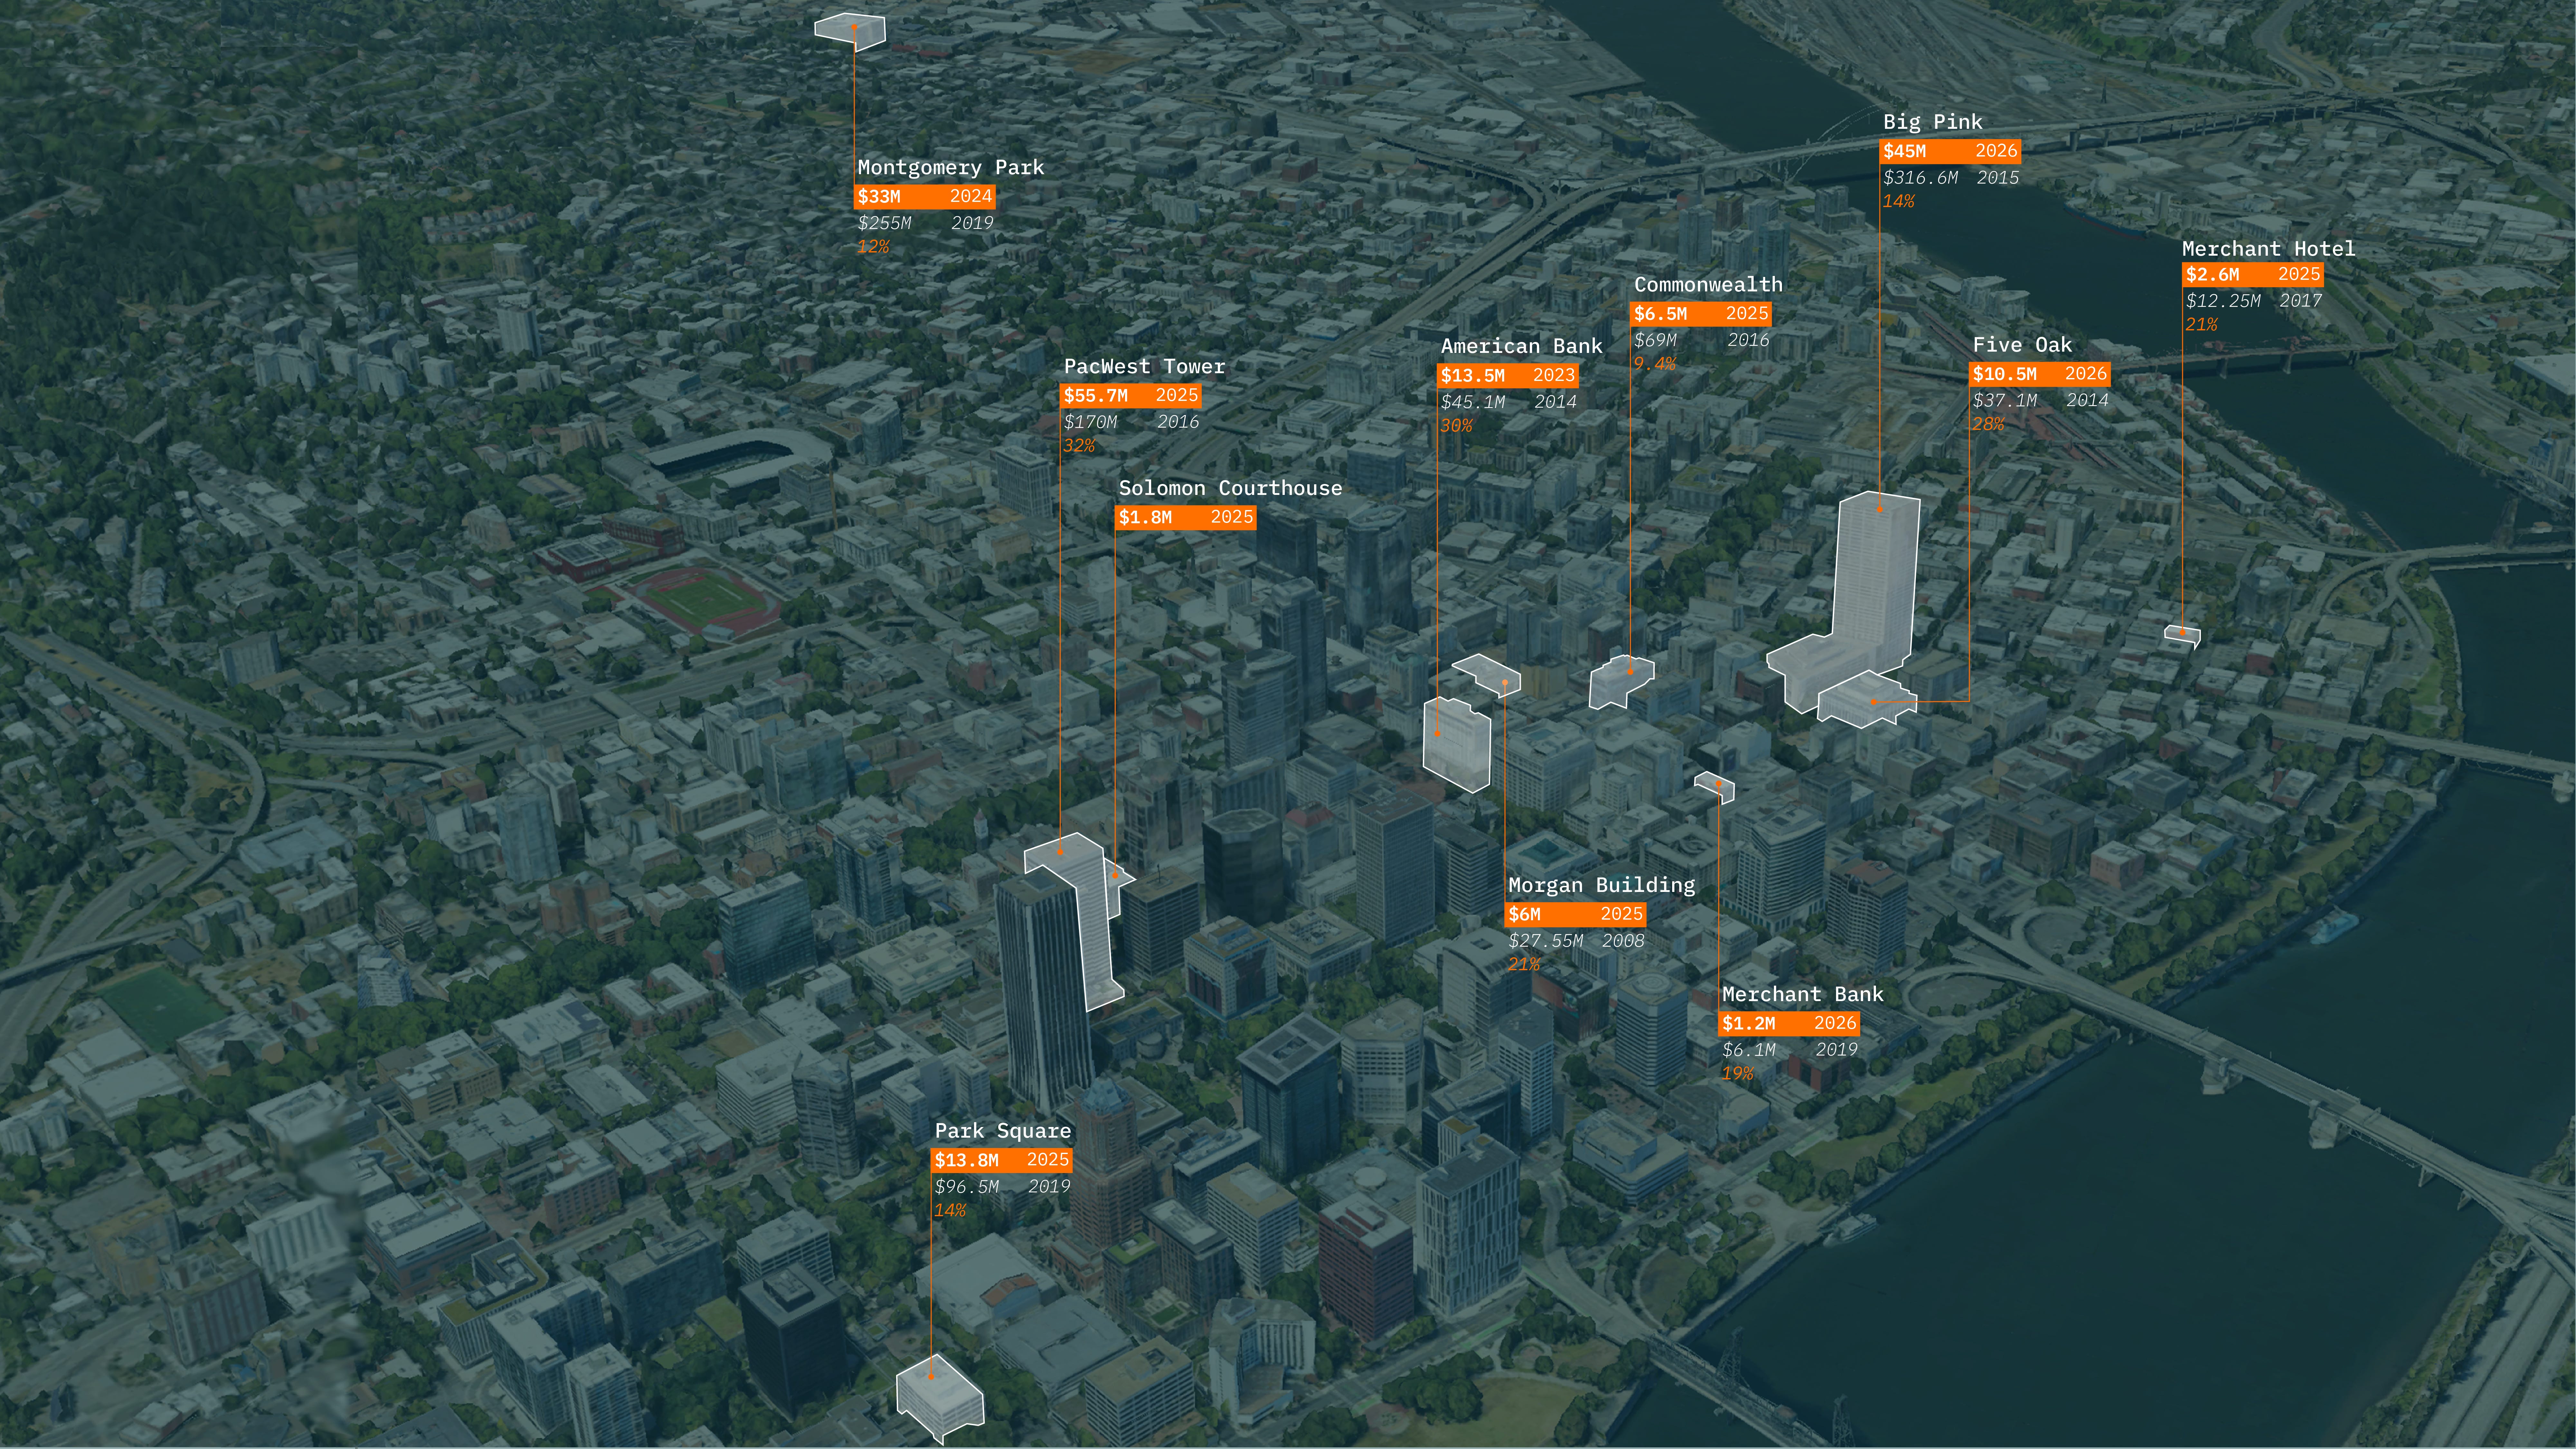
The Commonwealth most recently transacted for $6.5 million, 57% below its assessed value, and 9.4% of its previous transaction cost.1 The story of the Commonwealth building is uniquely ironic – how it tidily bookends the office era – but it is just one in a wave of similar transactions.
The Merchant Bank building sold in March of this year for $42 /sf. The Morgan Building, Park Square, and the Solomon Courthouse all sold in December of 2025, costing between $11 and $47 /sf. Montgomery Park went for 87% off its previous price in a courthouse auction. Jeff Swickard picked up Big Pink and Five Oak – a total of 1.38 million square feet in downtown Portland – for about $55 million total, all cash.
These are good buildings; many of them genuinely fine ones. They are historic, familiar to anyone who has spent time in downtown Portland. The wave of fire sale transactions is not a symptom of low building quality – it is a sign of the financial climate nationwide. Pre-COVID leases are expiring and buildings are emptying out, right as institutional debt matures into a stubbornly high interest rate environment, making refinance impossible (more on that here).
Owners who held onto their hopes for post-COVID recovery are finally giving up, or lenders are forcing a sale. “We’re six years from the shock of Covid,” Jim Costello, an executive director at MSCI – a company that analyzes commercial real estate data – said in a recent Wall Street Journal article. “That’s how long it takes someone to capitulate and give up such a highly valued asset.” Across the country, investors bought up 204 distressed office buildings in 2025, up from 133 the year before.
Who is Buying Portland?
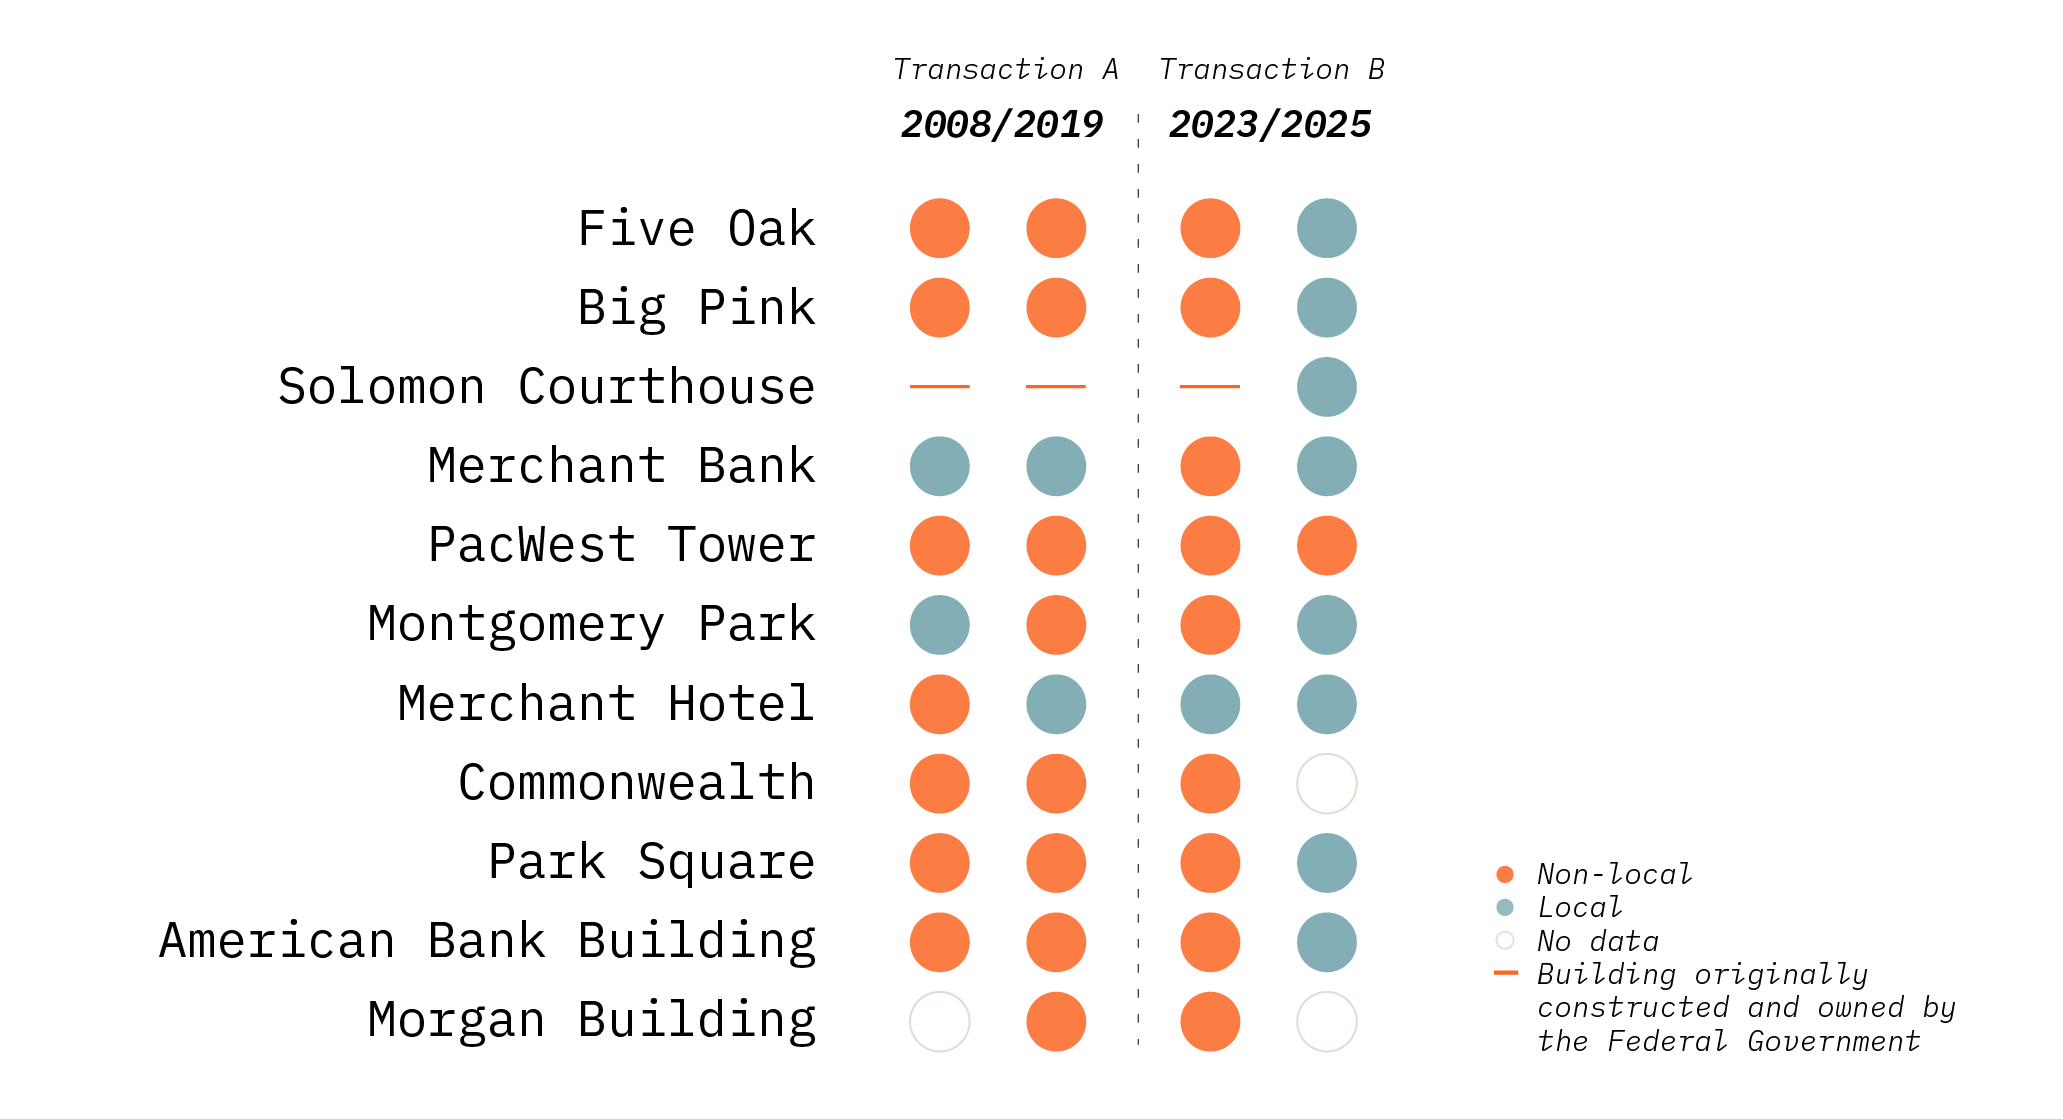
We traced eleven downtown buildings through their last two sales, to understand the relationship between “Transaction B” (the most recent sale) and “Transaction A” (the previous sale).
Across all of the buildings, the average price per square foot of Transaction A was $263, while Transaction B averaged $47. There is a certain shock that comes from seeing buildings trade for less than a fifth of their previous value, but a more interesting trend emerged beneath the sticker price. Across the Transaction A cohort, only two of the buyers were local. Every other transaction went to a non-local investor. When our city was on its way up, from 2008-2019, Portland’s downtown buildings became line items in portfolios managed from Zurich, New York, Munich, Dallas, Houston, Newport Beach, Santiago.
On the way down, only one went to a non-local buyer (two were bought by an anonymous LLC with a Beaverton PO Box). These buyers are familiar to you – restaurateurs, entrepreneurs, a naturopathic medical university, family real estate firms with generations in the city. Portlanders are buying up Portland’s downtown.
Two Kinds of Value
Every investor cares about the numbers, but local and non-local entities tend to see buildings differently. A building represents two different and simultaneous kinds of value – its use value (a function of what it does for its occupants, the reason people pay money to lease it, the operating income it yields for its owner) and its exchange value (the cost to acquire it, and the price it will fetch on the real estate market). No one sees exclusively one or the other, but institutional real estate investors – those non-local firms that hold large, nation-wide portfolios – tend to prioritize exchange value.
The standard tool to estimate the intrinsic value of a building today is a discounted cashflow (DCF) model, which is based on the building’s projected future cashflow. The math starts with a simple assumption: a dollar tomorrow is worth less than a dollar today.2 How much less is set by the discount rate, which reflects risk. At a standard 15% discount rate, a dollar of income one year out is worth 87 cents now; five years out, 50 cents; ten years out, 25 cents.
Every prospective deal is compressed into a standard score, the internal rate of return (IRR), which models the investment’s projected yield. That metric is typically calculated over a five- to ten-year hold period, which aligns with standard commercial real estate investment business plans and exit strategies. If an investor needs to see a 16% return in 7 years, and they can estimate a building’s risk, they know exactly how much it is worth to them right now.
IRR is useful for apples-to-apples comparison of investment opportunities, and even to compare a building with any other financial asset. Real estate can be considered next to a treasury bond, for example, based on its risk and return profile and the time horizon of its yields. In practice, that means an office tower in Portland has to compete for capital against data centers and energy infrastructure, as well as equities and bonds. When the demand fundamentals crack or risk increases or competing opportunities skyrocket – as office demand cracked in 2020 and data centers skyrocketed in 2025 – national investment capital is simply allocated elsewhere.
IRR introduces a bias for quick returns. Because it is based on DCF, and DCF assumes the present value of future dollars decays, IRR rewards how fast money comes back, not necessarily how much money comes back over the long haul. In fact, there is no reason to hold a building for the long haul, because cash received early is counted at full value while the value of cash received later withers to zero. Transactions modeled on a building selling at year seven will beat those modeled on a building held to year fifteen – even if the second building ultimately earns far more cash after year ten. The bias toward a short-term exit is compounded by the fact that most real estate investment capital is managed in closed-end funds that owe money back on a fixed timeline. Exit is deliberately scheduled, and it is not optional.
Until 2019, institutional capital made big, skyline-shaping bets on Portland, bringing us projects like Block 216 and scooping up icons like the Commonwealth building. But the standard DCF/IRR modeling did not factor COVID and hybrid working into its risk profile when calculating the discount rate. Buildings emptied, and soon debt built on the premise of a short-term exit came due. Unable to cover costs or refinance, all but one of the buildings we analyzed went back to their lenders between 2020 and 2025. No bank wants an underperforming asset on its balance sheet for long, so they put their Portland buildings on the market, priced to move quickly. Hence the fire sale.
Institutional investors around the country have chalked up their Portland bets as failures, and they’ve moved on. PwC and ULI’s Emerging Trends in Real Estate, 2026 ranks Portland 80th of 81 U.S. markets, second-to-last for the second year running. The judgement of nearly two thousand investors, developers, brokers, and lenders across the country suggests that non-local funds have no interest in allocating their capital here any more. That’s certainly what we saw when we mapped Transaction B. But we also saw that local investors do have an interest in Portland.
Local money
This is not a jingoistic celebration of local ownership.3 Rather, it’s an argument for understanding the holding patterns and the risk and return expectations that define local investors’ rational behavior. The choices they make will shape our city’s next decades.
Local principals expect to own a building for its whole life, not just a fund cycle. As a result, they tend to prioritize operating income (associated with use value), not exit price (exchange value). For a lifetime owner, a building is a slow, revenue generating asset to be maintained, not a one-shot capital event that must yield returns before an exit at year seven. A building held this way is an option on every use the city might need in the future – and a fire-sale basis is the cheapest option premium ever offered.
All of the local buyers we observed own more than one building in the Portland area, and most own multiple buildings just in the downtown. A single-asset institutional owner hardly pays attention to the neighborhood, and if they do, they see it as an externality. An owner with a multi-building portfolio has already begun to internalize neighborhood factors, whether they’ve noticed or not. What happens with one building affects the other.
They care about the place. That sounds soft and qualitative – and in some ways it is – but that is not the only interpretation of care, and it does not diminish the influence of care in decision-making. A restaurateur bought the Old Town building his pizzeria has anchored for decades; a university bought the complex it means to occupy. These are owners whose businesses are intimately tied to the use value of the buildings they now own. If institutional investors held Portland real estate as a line item, the new generation of owners hold Portland buildings for their details and specificities.
For these three reasons – longer horizons, portfolio exposure, and personal stakes – local money is poised to rebuild downtown. It still might. But there has been little, if any activity in the buildings we studied. Why?
Recovery is a choice
Newly minted building owners have essentially four options.
Sell. The buildings have recently transacted for pennies on the dollar, and, with national capital wary of repeating its ‘Portland mistake,’ the total addressable market is tiny. Selling takes time, cost, and effort. → No
Upgrade. Putting more money into an office building only makes sense if it will command a premium that pays back the investment. In Portland that is unrealistic. The businesses that would fill it are struggling or moving away. There is roughly an equilibrium between businesses and spaces – no influx means no competition to win with a premium space. Upgrading buys an empty floor. → No
Hold. Keep the building as-is, lease what you can, and wait for demand to increase. Even a building that is less than half occupied can cover its operating costs, maybe even eke out a return on cost inside of fifteen years. Maintenance can be deferred and taxes barely increase, so waiting is cheap and has no deadline. → Yes
Convert. This option is tricky, for a few reasons. Most conversions run into issues with the size of the floor plate, MEP systems, facade treatments, seismic risk categories, and access. These are knowns, priceable because they are tangible. Regulatory issues are unknowns. Permitting is a wildcard, subject to delays and conflicting departmental demands; it is hard to predict approval timelines. The Design Commission may not exist (in any recognizable form) by the end of 2026. Finally, because the future converted use has an entirely new tenant base, its financial returns are difficult or impossible to predict (but they are likely to be poor, because no single building conversion can generate tenant demand on its own). The one certainty in conversion is that money is leaving the owner’s hands. For all of these reasons, converting any single building is irrational. → No
The final answer is to hold. Even well-capitalized new owners are leasing what they can lease and waiting for the market to improve. The smartest money in the market is using this strategy, and it is perfectly rational on its own terms. It has worked for decades; to date, the cycle has always turned.
That is to say, the hold option is based on the premise of cycles. We’ve argued before, however, that that premise is faulty; demand patterns have fundamentally changed. After six years of holding and hoping for a post-COVID recovery, no one seriously believes office work is coming back in full force. The case is closed.
The logic also starts to break down at the district scale. If every building owner waits for the next cycle, the next cycle will never come. A downtown full of half empty buildings is not an attractive place to be. Each individual owner may be making a rational decision, but the net result is all of them suffering.
So there is a dissonance. The only apparently viable option, holding, doesn’t make sense at a longer time frame and a larger district scale. In fact, it is the riskiest strategy available for the owners that now carry the keys to Portland’s downtown. Holding on to an office building as an office building is the only path that’s actually been tested, and it has proven not to work.
The only way to break the paradox is to change the input assumptions. Selling depends on outside capital, and upgrading depends on increased demand for premium offices from well-funded companies expanding in Portland. Both are far outside of our control. The impasse will only break when the cost and uncertainty of conversion – things we can control – diminish.
Running the “doom loop” in reverse
The “doom loop,” – a spiral of vacancy, falling rents, distress, tax erosion, and urban decline – cascades because one building’s failure increases the odds of its neighbors’ failure. Boarded up windows degrade the whole block. The post-COVID pattern proved that buildings in a district are enmeshed: each one’s viability is a function of what surrounds it.
That mechanism can run in reverse.
Of course, a full building doesn’t automatically upgrade its neighbors – its vibrancy is necessary but not sufficient. Direct benefit comes only when the building uses are complementary, because each de-risks the other. A cluster of uses (say, childcare, grocery, housing, restaurant, and a park) in a meaningful geography each have an easier time leasing up. When these kinds of clusters are programmed together with the residents and businesses who already know the place and who will actively support those new uses, risk dips even further. A conversion that can’t pencil against today’s tenant demand pencils just fine if lease-up is close to certain, and that happens when buildings complement each other.
Risk spreads across a portfolio. Instead of a single building owner making a risky bet to convert a single property, a group of building owners make a coordinated bet on a cluster of properties – or, a “portfolio.” Each use is viable because the others exist; each succeeds because they all do.
The importance of coordination
Just about every celebrated turnaround of this kind had a singular protagonist – in Detroit, it was Bedrock Development, in London, Related-Argent is reimagining King’s Cross. These entities have concentrated land, patient equity, and most importantly, they can single-handedly balance complementary uses.
Portland’s fire sale isn’t producing a Bedrock or Related-Argent; it is producing a dozen local owners with aligned incentives – but no coordinating institution. The project ahead of us is untried: catalytic development through coordination rather than consolidation.
The new generation of owners has the difficult task of cooperatively creating district-scale places. Imagine property owners deciding to convert three buildings, demolish one for a purpose-built replacement, and upgrade one as flexible office, but only after the first buildings have stabilized.
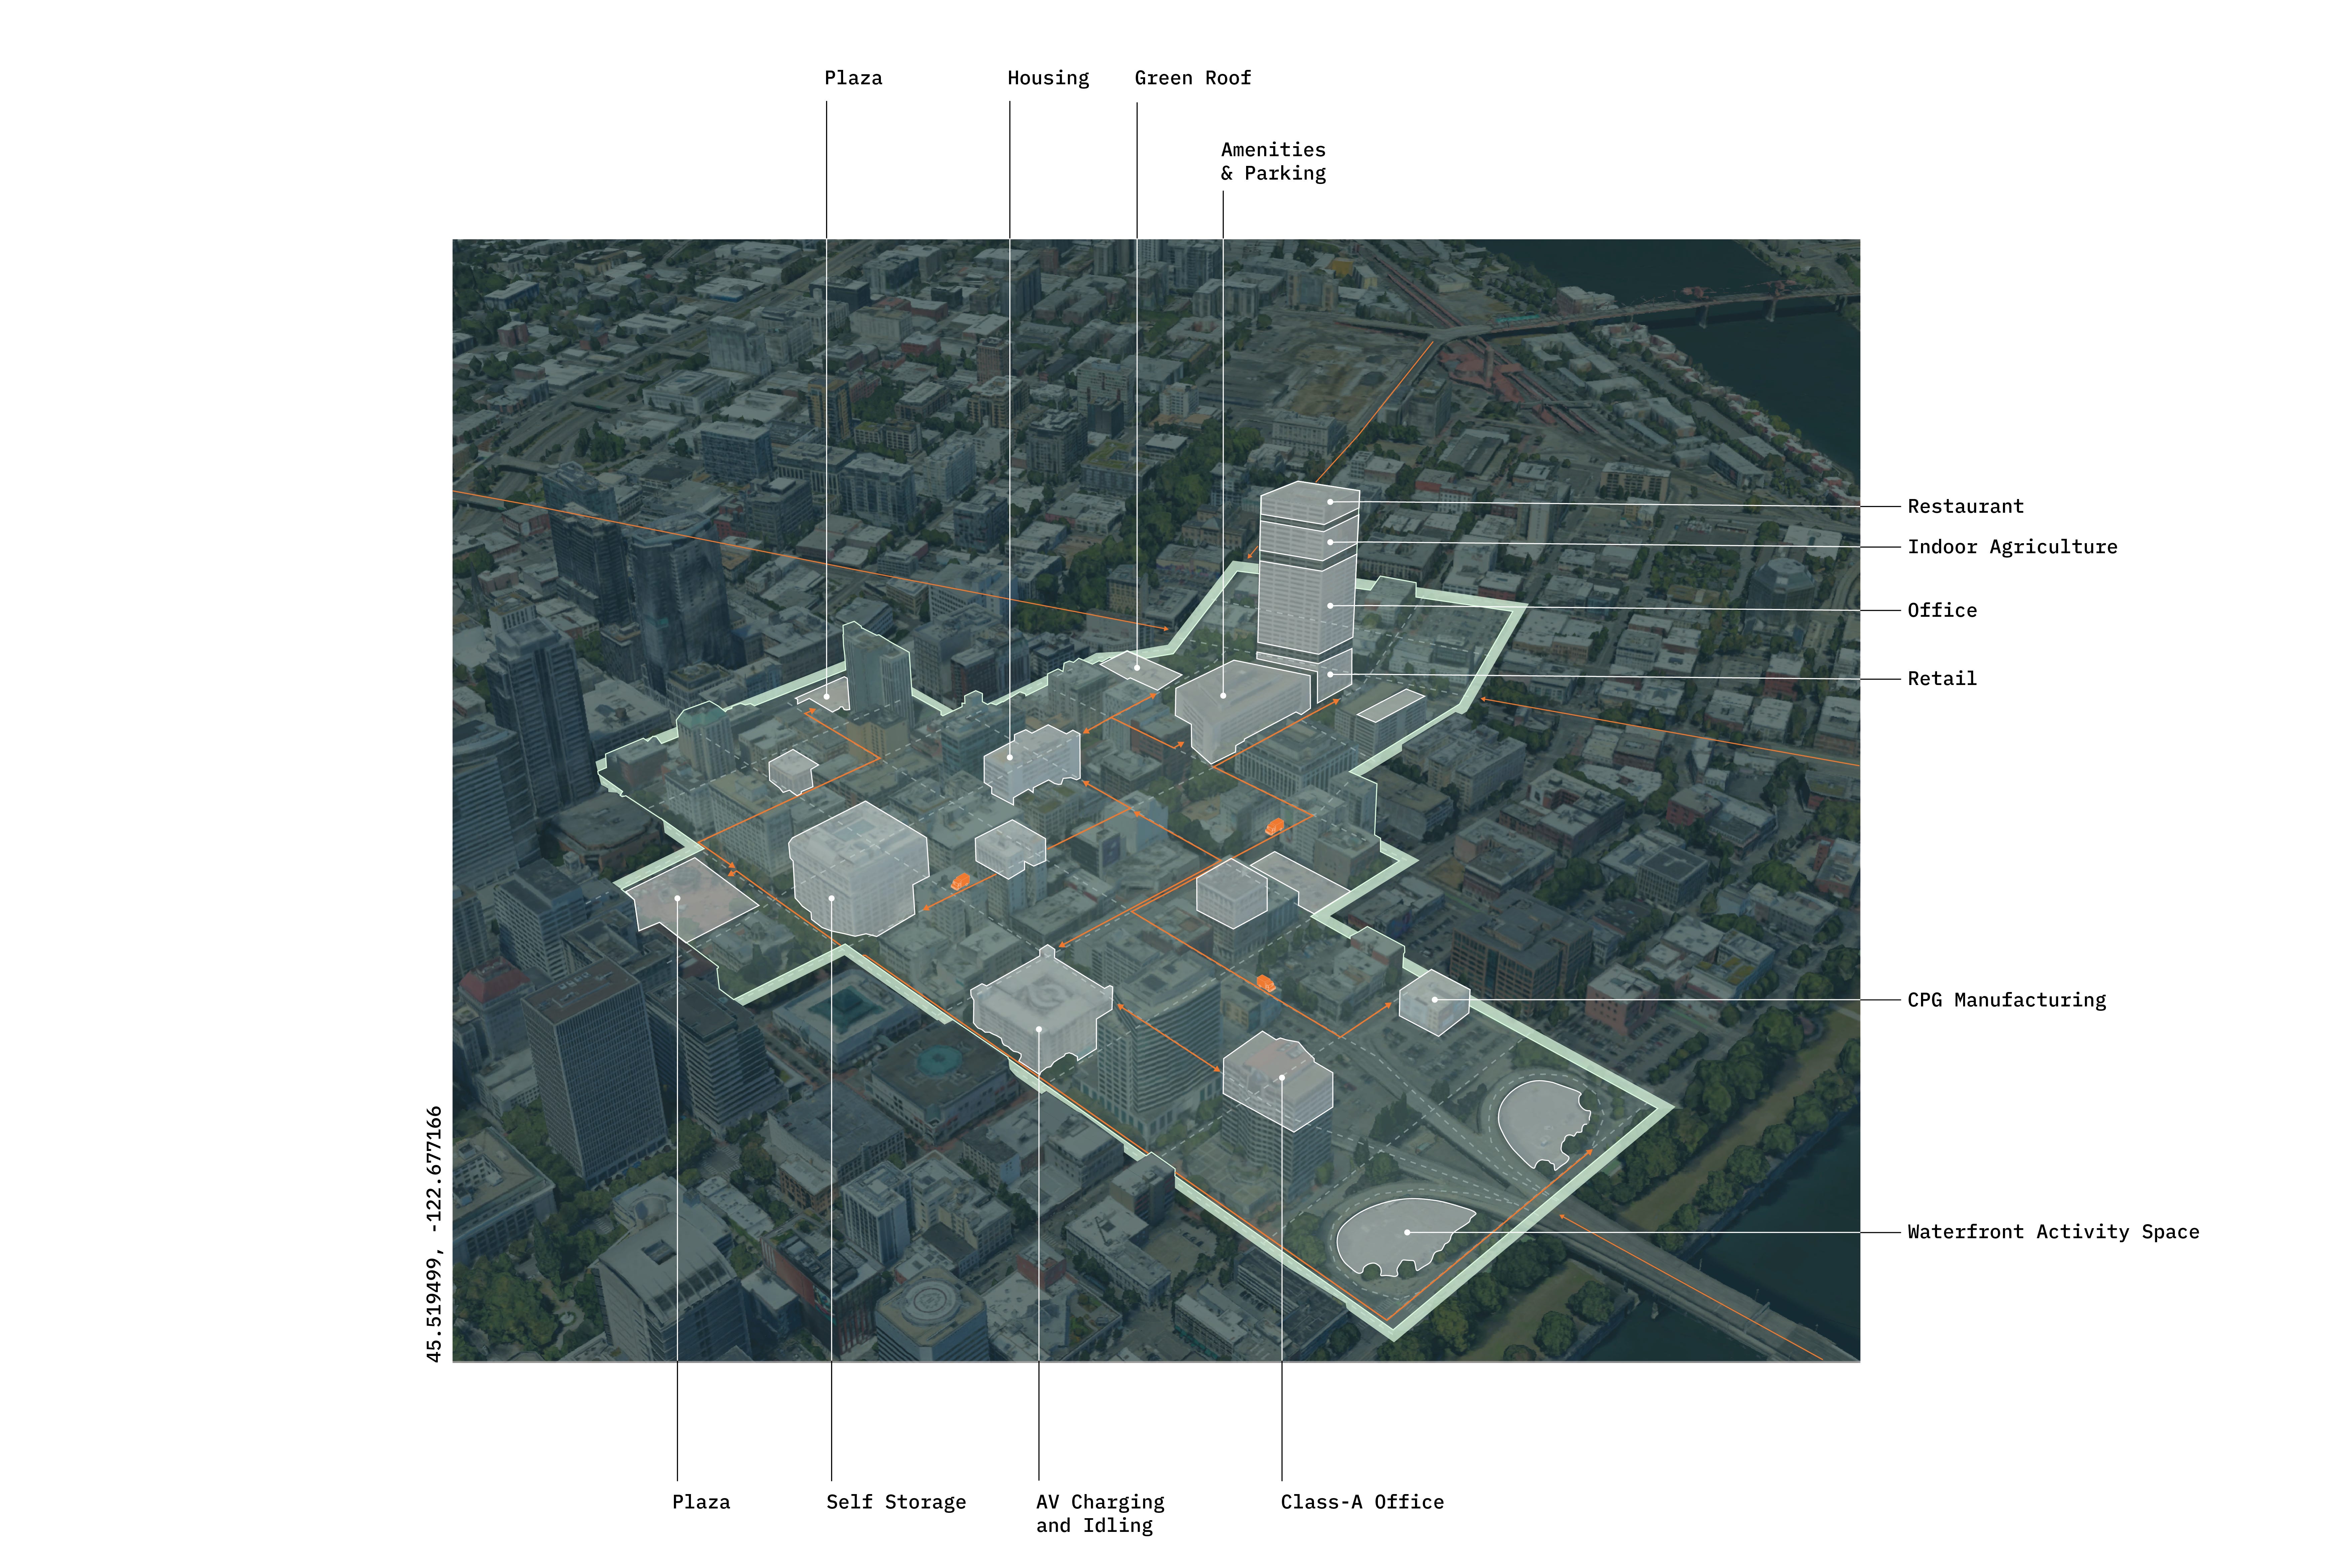
This kind of coordination could happen two ways. The first is through a light collaborative planning effort across the ordinary real estate market. Existing owners and new buyers align investments, share models of projected returns, and sequence complementary uses. This would require no new institutions and no legislation – only a coordinating entity that helps individual owners treat adjacency as information.
The other path, more similar to Bedrock or Related-Argent, would be a special purpose vehicle focused on district recovery. A corridor trust, for example, could syndicate a fund and acquire property across a defined geography. It would make decisions about building uses with the input – even the investment – of residents and local businesses.4 Each building’s capital stack would be broken into discrete time tranches, such that short-horizon money takes years one through five, mid-horizon equity takes years six through twelve and long-horizon stewards – families, endowments, the city itself – carry years twelve and beyond. These breaks are natural moments for another conversion if usage patterns shift significantly. This is not exotic; Albina Vision Trust is already testing cohesive design and community-centered stewardship at the district scale.
It also means reimagining what downtown is for. Buying at a low basis creates extraordinary flexibility. This is already starting to happen in cities around the country. In Washington D.C., a 940,000 sf federal building is becoming housing. In Chicago, a 485,000 square foot office building is becoming an urban vertical farm. “The buy-in at this distressed price allows us the opportunity to afford change,” real-estate developer Marc Calabria said to the Wall Street Journal. He recently bought the building for $4 million, after it sold for $68.1 million a decade ago.
Creative conversions like Calabria’s only work when the entry price is historically low – and that’s exactly what we are seeing in the Portland fire sale. It gives us a license to experiment.
The work remaining
Now is the moment to imagine new, creative, and coordinated uses of our downtown real estate. This kind of place-based transformation is harder than anything the industry has attempted in at least half a century.
For decades, commercial real estate has performed like a bond: steady and dependable. A new breed of real estate investors need to perform more like hedge funds, seeking out risk positions that others cannot manage and making active interventions to generate returns. Owners need to manage risk asymmetrically, which demands more imagination, agility, and local attunement. Suddenly use value matters a whole lot more than it did in a purely financialized approach. The next chapter of real estate will reward those owners who have a fundamental understanding of their buildings and the people who use them – a skill set that blends financial, physical, and human-centered capabilities.
There is no doubut that this transformation will benefit Portland and its residents in the long run. But this is not a charity case; no one is being asked to burn cash for pure public benefit. Coordinated, catalytic investment will yield significant returns for those who bought buildings at a historically low price. The ask is much simpler: “price in” the surrounding district, and make coordinated investments in creative conversions.
None of this makes conversion easy. There are a host of physical challenges, and the regulatory environment is fickle. Coordination will require a clear owner with new templates and broad buy-in.
Field States is actively engaged. We are building a rigorous, standardized method for measuring conversion cost, making options priceable. We are creating district-scale demand modeling, so complementary lease-up can be underwritten. And we are working directly with owners, kickstarting the coordination process inside the ordinary operations of the local market.
Our goal is to put Portland’s existing square footage to work. We are here to partner with the ambitious vanguard of new real estate investors to build value in our communities. Now is the moment to choose what the recovery looks like – and everyone making that choice is already here in Portland.
The buyer who paid $69 million for it in 2016 lost their equity in a 2023 foreclosure when the building went back to the lender.
The financial analyst’s version of “a bird in the hand is worth two in the bush.”
Serious problems arise when a closed economic ecosystem is deprived of outside capital. Other states have a clear focus on attracting foreign direct investment, even luring Oregon businesses away with incentives and targeted recruitment, according to a recent study from the University of Oregon.
Portland’s Community Investment Trust has become a national lighthouse by proving that people can benefit from investing in their own neighborhood real estate.
Well written and spot on!
Thanks for this, I’ve been looking at the downtown real estate in my location and trying to understand what is happening. This is helpful in thinking about buyer motivations and overall neighborhood development